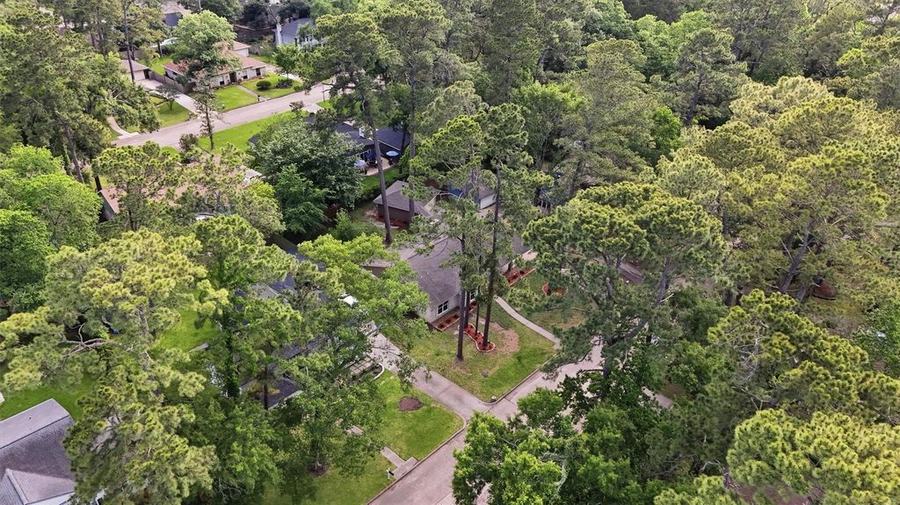
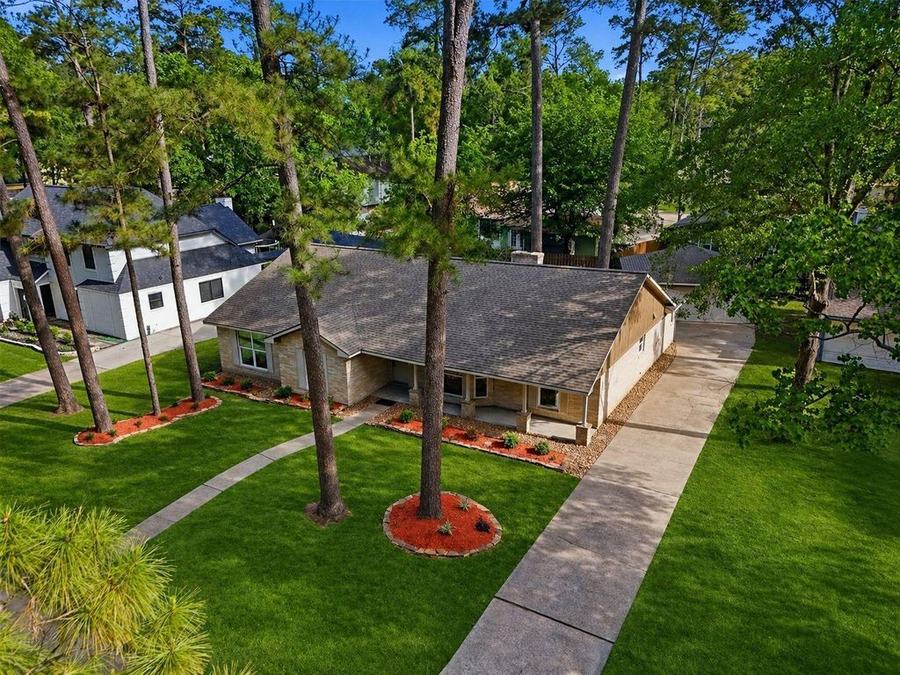
A single-story brick home among tall pines in Trailwood Village, Kingwood

Houston homeownership center · The NACA homebuyer program

Your Path to Homeownership May Be Closer Than You Think.

Explore the NACA homebuyer program, understand its mortgage benefits and qualification process, and get guidance from The Michael O’Neal Group on finding your next home in Greater Houston.

  • No down paymentNACA says its mortgages are 100% of value. NACA
  • No PMIMembers don’t pay private mortgage insurance. NACA
  • No closing costs to the borrowerNACA says the lender pays them and doesn’t add them to the loan. NACA
  • No credit-score minimumNACA reviews payment history instead of a score. NACA

Eligibility and final loan terms are set by NACA and its participating lenders, not by us. Photo: a home from Michael’s listing in Trailwood Village.

Independent resource. The Michael O’Neal Group is an independent real estate brokerage team affiliated with Keller Williams Realty Northeast. This website is an independent educational resource and is not operated, sponsored, or endorsed by NACA. NACA determines program eligibility and mortgage qualification. Mortgage terms and program requirements are subject to change. Michael O’Neal is a real estate broker, not a NACA counselor, housing counselor or mortgage lender.

The NACA journey

Ten steps from “what is NACA?” to keys.

Tap a step for what happens, what to gather, who handles it, what slows people down and where our team fits. NACA, not our brokerage, decides qualification.

Pick the step you’re on to see your progress.

  1. 01Explore the program
    What happens
    Read how the NACA purchase program works: housing counseling plus one fixed-rate mortgage, with membership required for the mortgage.
    Documents
    Nothing yet.
    Who handles it
    You.
    Common delays
    Mixing up NACA with grant programs or down-payment assistance. NACA is a mortgage with counseling, not a grant.
    How Michael’s team can help
    Answer the questions in "Could NACA be an option?" below and talk through the home-search side with us.

    Official source: NACA purchase program

  2. 02Attend a free NACA workshop
    What happens
    NACA’s free homebuyer workshop is about four hours, in person or self-paced online. NACA says each office holds at least two a month, mostly on Saturdays, and a seat should open within six weeks.
    Documents
    None. NACA says you don’t bring financial documents. Bring something to take notes.
    Who handles it
    NACA.
    Common delays
    Waiting for an open seat. If you want an outside agent, that agent must upload your buyer representation agreement in NACA’s portal before you attend.
    How Michael’s team can help
    If you want us as your agent, tell us before you register so your agent can complete NACA’s portal steps first, with your permission.

    Official source: NACA workshop sign-up

  3. 03Create a NACA member account
    What happens
    You set up the member portal (a cellphone is required for two-factor security), sign NACA’s agreement, enter your information and pay the membership fee.
    Documents
    A cellphone, photo ID, and the details NACA’s portal asks for.
    Who handles it
    You, in NACA’s portal.
    Common delays
    Unfinished portal sections. NACA lets you schedule intake only after they’re complete, including the membership fee and credit report.
    How Michael’s team can help
    We never ask for your login, credit report or documents. We can remind you of the steps you’ve said are left.

    Official source: NACA purchase steps

  4. 04Meet with a NACA counselor
    What happens
    Intake is about two hours, at an office or by video. The counselor reviews your budget and documents and sets a payment you can afford.
    Documents
    Photo ID for each person if a joint credit report will be pulled, plus your uploaded documents.
    Who handles it
    Your NACA counselor.
    Common delays
    Missing documents or a follow-up scheduled weeks out. NACA says to expect follow-up within about 30 days.
    How Michael’s team can help
    We can help you think through neighborhoods and price ranges that fit the payment your counselor sets.

    Official source: NACA counseling department

  5. 05Complete financial and documentation requirements
    What happens
    Work through your counselor’s action plan and NACA’s participation pledge, including at least one activity before qualification.
    Documents
    30 days of pay stubs, two years of tax returns and W-2s, three months of statements for every account (12 months if self-employed).
    Who handles it
    You and your counselor.
    Common delays
    Liens, charge-offs or collections that must be resolved; NACA says liens to be paid can add time.
    How Michael’s team can help
    We keep a checklist of what you’ve told us is still open, if you enroll in our follow-up.

    Official source: NACA qualification FAQ

  6. 06Receive NACA qualification
    What happens
    NACA Qualified means NACA has pre-approved you for its mortgage and you may start the housing search. NACA says many active members are qualified in about three months, and it shouldn’t take more than six without circumstances such as a recent foreclosure.
    Documents
    Whatever your counselor still lists as open.
    Who handles it
    NACA.
    Common delays
    Recent foreclosure, bankruptcy, charge-off or liens. Qualification is not a closed loan; lender conditions still follow.
    How Michael’s team can help
    We can’t grant or speed up NACA qualification. We get your home search ready for the day it comes.

    Official source: NACA qualification FAQ

  7. 07Attend the required purchase workshop
    What happens
    After qualification, NACA requires a Purchase Workshop covering the search, contracts and the mortgage file, described as Thursdays from 6 to 7:30 p.m. at an office or online.
    Documents
    Your qualification details.
    Who handles it
    NACA.
    Common delays
    Not registering right away after qualification.
    How Michael’s team can help
    Bring us your notes; we’ll line them up with how Houston contracts work.

    Official source: NACA purchase steps

  8. 08Search for homes with a participating agent
    What happens
    Search within your NACA-approved payment and loan limit. NACA says members working with an outside agent are referred back to that agent on qualification, if the agent uploaded the agreement before the workshop and you weren’t already a member.
    Documents
    Your NACA-approved maximum payment and the property rules your counselor gave you.
    Who handles it
    You and your real estate agent.
    Common delays
    Homes over the payment or limit, or census-tract rules for non-priority members. NACA says you can’t pay cash to get over the maximum.
    How Michael’s team can help
    Search, showings, neighborhood and tax research, and offers: this is where our team does the most work.

    Official source: NACA real estate FAQ

  9. 09Complete property and lender requirements
    What happens
    NACA doesn’t allow waiving the inspection contingency. Repairs can be financed in a repair escrow and completed after closing. The lender won’t lend more than the appraised value.
    Documents
    Inspection report, contract, repair bids if needed.
    Who handles it
    The lender, NACA and you, with your agent.
    Common delays
    Appraisal gaps and repair scopes. NACA targets about 35 days from contract for homes without major repairs and 45 to 60 days with them.
    How Michael’s team can help
    We coordinate inspections, repair negotiations and deadlines from contract to closing.

    Official source: NACA real estate FAQ

  10. 10Close and receive the keys
    What happens
    NACA says you close with an approved settlement agent at the local NACA office, and leasebacks aren’t allowed: you take possession at closing or funding.
    Documents
    ID and the funds NACA lists: earnest money, inspection, prepaid taxes and insurance, reserves.
    Who handles it
    The settlement agent, lender and NACA.
    Common delays
    Late conditions from the lender or repairs on the property.
    How Michael’s team can help
    We keep the closing date in view and walk the home with you before closing.

    Official source: NACA real estate FAQ

Steps and timing are NACA’s published descriptions (checked Nov. 6, 2026, and NACA’s Real Estate FAQ, read Nov. 5, 2026). NACA also describes a Property Workshop webinar before qualification. Timelines are NACA’s ranges, not promises.

Readiness check

Could NACA be an option for you?

Eight quick questions and an educational summary, right away and with no sign-up. This isn’t an application: nobody is approved, qualified or denied here. NACA decides eligibility.

1. Will the home be your primary residence?
2. Does anyone who will live in the home own a home or other property now?
3. Household income, roughly
4. Where in Greater Houston?
5. Estimated purchase budget
6. Are you open to NACA’s required counseling and workshops?
7. When would you like to buy?
8. Are you already working with NACA?

Mortgage benefits

What NACA says its mortgage includes.

NACA’s published terms, in plain English. Tap “Learn more” for the fine print and the official page.

No down payment

NACA says no down payment is required and its mortgages are 100% of value, and that no down payment doesn’t raise the rate.

Learn more

Zero down is not zero cash. NACA’s mortgage FAQ lists funds members still need: earnest money (returned at closing), a home inspection, prepaid insurance and taxes, and reserves. See “What does it really cost?” below.

NACA mortgage FAQ

No PMI

Private mortgage insurance protects a lender when a borrower puts little down; it’s usually a monthly charge on conventional loans with under 20% down. NACA says its members don’t pay PMI.

Learn more

In its place NACA describes a free Membership Assistance Program for as long as you have the NACA mortgage. NACA also records a $25,000 soft-second lien to support its occupancy rule.

NACA purchase product

No credit-score cutoff

NACA says it doesn’t consider a credit score. It reviews your own payment history, income, debts and savings pattern.

Learn more

Payment history still matters a lot: NACA says the housing or rent payment matters most. Counseling identifies items to resolve; nothing here promises a deleted account or an approval.

NACA purchase product

Fixed-rate mortgage

NACA’s mortgage is always fixed, for 15, 20 or 30 years, so principal and interest don’t change over the life of the loan.

Learn more

On Nov. 5, 2026 NACA’s home page listed 6.25% for 30 years, 5.75% for 20 and 5.875% for 15; its purchase-product page lists different rates for higher-income members. Confirm which rate applies to you.

NACA home page

Optional rate buy-down

NACA offers an optional buy-down: extra funds paid at closing permanently reduce your fixed rate.

Learn more

NACA’s own documents describe the buy-down math differently, so we don’t publish a formula. Ask your NACA counselor for the current terms before you plan around it.

Qualification workbook 26.6

Housing counseling

NACA says its counseling subsidiary is a HUD-approved intermediary and its counselors are HUD-certified. Basic counseling and the workshop are free.

Learn more

The counselor reviews your budget and documents, sets an affordable payment and gives you an action plan. That’s housing counseling, not paid credit repair.

NACA counseling department

Membership is required for the NACA mortgage. NACA lists the annual membership fee as $36 per household (another NACA page still says $25; confirm before paying). Eligibility and fees FAQ

Compare loans

NACA, FHA, conventional and VA, side by side.

An educational comparison, not a quote. Every rate is editable: NACA’s starts at its published 30-year rate (Nov. 5, 2026); the others start at Freddie Mac’s weekly average (Oct. 22, 2026), which no lender is bound to. Not every buyer qualifies for every loan.

Interest rates (edit any)

FHA mortgage insurance: HUD Mortgagee Letter 2023-05 (annual MIP), HUD Handbook 4000.1. VA funding fee: VA.gov, VA funding fee and loan closing costs (page updated Oct 5, 2026). NACA’s lender-paid closing costs, no PMI and no down payment follow NACA’s published terms.

Payments exclude anything left blank. “Upfront funds” here is the down payment plus closing costs you entered; every loan, NACA included, also needs earnest money, inspection, prepaids and possibly reserves (see the next section). Want more detail? Use our loan comparison, FHA, VA and mortgage calculators.

What does it really cost?

No down payment isn’t no money.

NACA’s terms remove the down payment, PMI and lender closing costs. You still need cash for other things. Estimate yours with clearly labeled assumptions you can change.

How this works: NACA says members need earnest money (returned at closing), an inspection, prepaid property insurance and taxes, and reserves: one month if your payment rises less than $300, two months if it rises more. The prepaid months are illustrative assumptions; your lender sets the real figures. Membership is $36 a year per household. NACA also describes a nominal credit-report fee that the lender refunds at closing; NACA doesn’t publish the amount. Starting values are examples, not Houston averages. NACA mortgage FAQ · Fees FAQ

The NACA process isn’t free from start to finish: there’s membership, the funds above, and your own time for workshops, counseling and documents.

Credit readiness

Credit challenges don’t always mean homeownership is out of reach.

NACA’s underwriting looks at your actual payment history, income, debts and savings instead of a credit-score cutoff. That’s different from traditional score-based underwriting, but your history still matters.

1

Payment history

NACA reviews how you’ve paid, especially rent or housing. Twelve on-time months of rent tell a clearer story than a score.

Do this: Keep every payment you control on time from today.

2

Debt obligations

Monthly debts reduce the payment you can afford. Your counselor compares income with what you owe each month.

Do this: List every monthly payment, its balance and its due date.

3

Budgeting

NACA’s counselor sets a payment with you from your real budget.

Do this: Write a month of spending, then a target budget with the new housing payment in it.

4

Savings patterns

NACA looks at your savings pattern. Saving steadily also builds the cash you still need at closing.

Do this: Set an automatic transfer, even a small one, each payday.

5

Collections and liens

NACA says liens that have to be paid can add time to qualification.

Do this: Gather the collection letters and lien notices you have for your counselor.

6

Credit-report errors

You can dispute errors yourself, for free, with the credit bureaus. The CFPB warns about paid credit-repair companies that promise what they can’t deliver.

Do this: Get your free reports and note anything that isn’t yours.

7

Preparing for counseling

Counseling goes faster when documents are ready.

Do this: Collect pay stubs, tax returns, W-2s and three months of statements before intake.

Nothing here promises credit repair, a higher score, deleted debts or approval. Housing counseling through NACA is separate from paid credit repair. CFPB: counseling vs. credit repair · CFPB: HUD-approved housing counselors

Keeping it real

The Good, The Bad & The Reality.

The Good

  • Potential zero-down financingNACA’s mortgage is 100% of value.
  • No PMINo monthly private mortgage insurance.
  • Counseling supportFree basic counseling and workshops with HUD-certified counselors, per NACA.
  • No minimum credit scoreHistory, income and savings instead of a cutoff.
  • Fixed rate15, 20 or 30 years, always fixed.

The Bad

  • Extensive documentationPay stubs, two years of returns and W-2s, three months of every account.
  • Counseling requirementsWorkshops, intake, follow-ups and a participation pledge.
  • Lengthy preparationAbout three months for many active members, up to six or more with complications.
  • Geographic rulesNon-priority members are limited to certain census tracts.
  • Membership obligationsAnnual dues and five participation activities a year while you have the loan.
  • Property and purchase rulesLoan limits, no inspection waiver, NACA settlement agents, no leasebacks, and the home must stay your primary residence.

The Reality

  • A strong option for some buyersNACA can open a door for buyers with steady income and patience who don’t have a down payment or a high score.
  • Not always the fastestIf you have a down payment, good credit and a short timeline, an FHA, VA or conventional loan may close sooner.
  • Compare before you chooseRun both paths. The best loan is the one that fits your timeline, cash and goals.
NACAFHA / conventional / VA
Down paymentNone, per NACAFHA 3.5% minimum; conventional varies; VA can be zero for eligible borrowers
Mortgage insuranceNo PMIFHA has MIP; conventional PMI under 20% down; VA has a funding fee unless exempt
CreditNo score minimum; payment history reviewedLenders set score minimums
CounselingRequired workshops and counselingUsually optional (some programs require education)
TimelineQualification often about 3 months, then the searchPreapproval can take days once documents are in
Who decidesNACA and its participating lendersThe lender you choose

Michael’s take · broker opinion, not loan advice

NACA rewards patience and preparation. If you can work the steps for a few months, it can put a home within reach without a down payment. If you need to move fast, compare it with other loans before you commit.

Free download

The Houston Homebuyer’s NACA Preparation Guide

A printable guide to keep beside you: program overview, eligibility considerations, workshop registration, documents, a budget worksheet, a readiness checklist, the timeline, common questions, NACA’s Houston office and how to work with our team.

No sign-up needed. Prefer email? Use the form.

Email me the guide

Houston home search

Where will your next home be?

Explore our Greater Houston community guides. NACA eligibility isn’t set by neighborhood or ZIP: it can depend on your income, the property’s census tract, occupancy and other program rules, so we never label an area “NACA-eligible.”

The tree canopy over Trailwood Village in Kingwood
Photo from Michael's listing at 1914 Lazy Grove Dr, Trailwood Village.

Kingwood

Explore the villages, wooded streets, trails and homes that make Kingwood distinctive, with Michael O’Neal and The Michael O’Neal Group.

Community Guide
Historic rice silos, Katy
Illustrative photo of the area. Photo: Chday, CC0, via Wikimedia Commons.

Katy

Master-planned communities along the I-10 corridor.

Community Guide

Found a home you love?

Let us help you investigate whether it fits your homebuying plan.

We’ll look at the price, taxes, HOA and condition with you. NACA confirms whether the address and price work for your NACA status: use NACA’s ZIP tool for a general look and the FFIEC geocoder for the census tract.

Ask About a Home

The Michael O’Neal Group

You don’t have to navigate homeownership alone.

NACA handles counseling, qualification and the mortgage. We handle the house: the search, the neighborhoods, the offer and everything from contract to keys. The Michael O’Neal Group has helped 2,035 families over 13 years.

  • Understanding the home search
  • Exploring Houston neighborhoods
  • Finding homes that fit your NACA-approved payment
  • Evaluating property taxes and ownership costs
  • Negotiating offers
  • Coordinating inspections and repair requests
  • Navigating contract-to-closing requirements
  • Staying organized through the purchase

Want us as your agent on a NACA purchase?

NACA’s published rule: an outside agent registers in NACA’s Real Estate Agent Portal and uploads the buyer representation agreement before you attend the NACA Homebuyer Workshop. Then NACA refers you back to that agent when you’re NACA Qualified, if you weren’t already a NACA member before the workshop. NACA doesn’t charge the agent and doesn’t allow extra buyer fees. NACA Real Estate FAQ

So tell us before you sign up for a workshop. With your permission, your assigned agent completes NACA’s portal steps. We never sign you up with NACA or send your information to NACA without your permission. We are not a NACA in-house agent or NACA Referral Agent.

  • Brenda BeltranBrenda BeltranTeam Leader Partner
  • Kori Chesson-HerringKori Chesson-HerringREALTOR®
  • Elizabeth (Liz) DiazElizabeth (Liz) DiazREALTOR®
  • Anabel GarciaAnabel GarciaREALTOR®
  • Jose GarzaJose GarzaREALTOR®
  • Maria JanesMaria JanesREALTOR®
  • Antonio PaizAntonio PaizREALTOR®
  • Emma KerscherEmma KerscherTransaction Coordinator
  • Belinda RiosBelinda RiosAdministrative Assistant / Listing Coordinator
  • Zoey RothmeyerZoey RothmeyerInside Sales Agent (ISA)

Home Front Mortgage and Keystone Title & Escrow are affiliated businesses. Home Front is not a NACA lender, and NACA purchases close with NACA’s approved settlement agents. You never have to use an affiliated provider. Affiliated business disclosure · Client reviews on HAR.com

Buyer follow-up program

Stay on track with our team.

Join our follow-up program and your agent checks in at the milestones you share: workshop, counseling, qualification and the search. A secure online dashboard is in development; until it’s live, follow-up happens by text, call or email.

Preview with sample data. Not connected to any account.

Hi, Jordan

Step 5 of 10 · Financial and documentation requirements

Next action
Upload March bank statements to NACA’s portal
Upcoming
Counselor follow-up (date you share)
Your agent
Assigned team member, call or text
Neighborhoods
Humble, Atascocita
  • Pay stubs, last 30 days
  • Two years of tax returns and W-2s
  • Three months of statements, every account
  • Photo ID

Links: NACA purchase · Qualification FAQ

Video

Keeping It Real with Michael O’Neal: Understanding NACA

A short video is in production. It will cover what NACA is, why buyers consider it, what “no down payment” really means, why counseling matters and how our team helps with the home search. It will have captions and a transcript.

“NACA can put a home within reach without a down payment, but it rewards patience and preparation. Let NACA handle the mortgage; let us handle the house.”

Michael O’Neal

Questions

NACA questions, answered.

Can I buy a home with bad credit?

Possibly. NACA says it doesn’t turn people away for bad credit or no credit if they work through the items a counselor identifies. It reviews payment history, income, debts and savings. Nothing here promises approval.

Purchase product

Does NACA require a minimum credit score?

No. NACA says it doesn’t consider a credit score. It looks at your own payment history, especially rent or housing payments.

Purchase product · Qualification FAQ

Is NACA completely free?

No. The workshop and basic counseling are free, but membership is required for the mortgage ($36 a year per household on NACA’s eligibility FAQ), there’s a nominal credit-report fee the lender refunds at closing, and you still need earnest money, an inspection, prepaids and reserves.

Eligibility and fees FAQ · Mortgage FAQ

How long does NACA qualification take?

NACA says many active members are qualified in about three months and that it shouldn’t take more than six unless there’s a recent foreclosure, bankruptcy, charge-off or a lien to pay. The home search comes after.

Qualification FAQ

Can I use my own Realtor?

Yes. NACA works with outside agents. NACA says the agent registers in its Real Estate Agent Portal and uploads your buyer representation agreement before you attend the homebuyer workshop; you’re then referred back to that agent when you’re NACA Qualified.

Real Estate FAQ

What happens if I’m already working with NACA?

Tell us where you are in the process. NACA says the referral-back to an outside agent applies when you weren’t already a member before the workshop, so ask NACA how changing agents works for you; NACA’s FAQ says a new agent registers and uploads a new agreement after the old one is ended under its terms.

Real Estate FAQ

Can I buy in Kingwood or Atascocita with NACA?

It depends on you and the address. NACA says priority members (income at or under the area median) can buy anywhere in the metro area, while other members are limited to census tracts at or under the median. Check the specific address with NACA.

Area eligibility

Do I need money for inspections?

Yes. NACA lists a home inspection among the funds members still need, along with earnest money, prepaid insurance and taxes, and reserves. NACA also doesn’t allow waiving the inspection contingency.

Mortgage FAQ · Real Estate FAQ

Can I use NACA for an investment property?

No. NACA’s mortgage is for a primary residence you occupy for as long as you have it, and nobody in the household can own another property at closing. A two-to-four-unit home can qualify only if you live in one unit.

Eligibility FAQ · Real Estate FAQ

Can I compare NACA with other financing options?

Yes, and it’s worth doing. Use the comparison above and talk with lenders about FHA, VA or conventional loans. You’re free to choose any lender.

Loan comparison calculator

How does NACA handle property repairs?

NACA can finance required repairs in a repair escrow, completed after closing and paid to the contractor as work is inspected. NACA says the loan with repairs can be up to 110% of the after-repair appraised value, within your approved payment and the loan limit.

Real Estate FAQ

What happens after I become NACA Qualified?

You attend NACA’s Purchase Workshop, search for a home within your approved payment, sign a contract, complete inspection and lender requirements, and close with NACA’s approved settlement agent. NACA targets about 35 days from contract without major repairs.

Purchase steps · Real Estate FAQ

Answers summarize NACA’s own pages, linked under each one. NACA has the final word.

Reference library

The full NACA research, with every source.

Everything above comes from this research, checked against NACA’s public pages on Nov. 6, 2026. Open it for the details, including where NACA’s own pages disagree.

NACA determines eligibility. This page is general information from NACA’s own site and a few public housing references, checked November 6, 2026. It is not a NACA application, a preapproval, or a promise of a rate, a price, or an approval. Program terms change. Confirm every figure with NACA before you rely on it. Michael O’Neal is a real estate broker. He is not a NACA counselor, a lender, or a housing counselor.

What NACA is

A counseling program with one mortgage, not a grant

The Neighborhood Assistance Corporation of America (NACA) describes a purchase program built around housing counseling and a single fixed-rate mortgage it calls the Best in America Mortgage. NACA’s overview says its counseling subsidiary, the Neighborhood Stabilization Corporation, is a HUD-approved counseling intermediary, and its counseling department says its counselors are HUD-certified. Basic counseling and the homebuyer workshop are described as free. Access to the NACA mortgage requires membership.

Michael O’Neal works with buyers using the NACA program in Kingwood, Humble, Atascocita, Lake Houston and greater Houston. That is a working relationship with the buyer. It is not a NACA partnership, endorsement, certification, or affiliation, and it is not a statement that NACA has approved this brokerage.

Sources: NACA purchase program · NACA overview FAQ · Counseling department · General and eligibility FAQ

Published terms

What NACA says the mortgage includes

No down payment

NACA’s purchase page says no down payment is required and that NACA mortgages are 100 percent of value. It says the lack of a down payment does not raise the rate.

No closing costs or points

NACA says the lender pays closing costs, including appraisal and title, and does not add those costs to the loan. The purchase-product page lists no application fee and no points or fees.

No PMI

NACA says members do not pay private mortgage insurance. In its place, NACA describes a free Membership Assistance Program for as long as the member has the NACA mortgage.

Fixed rate, below the market rate NACA cites

The term is 15, 20 or 30 years, always fixed. NACA publishes more than one rate sheet. See the rates section below and confirm which rate applies to you.

Optional rate buy-down

NACA offers an optional buy-down that uses extra funds to permanently reduce the fixed rate. Two official NACA documents describe the math differently, so the formula is not restated here as a single rule.

No credit-score requirement

NACA says it does not consider a credit score. It says it reviews the member’s own payment history, income, debts and savings pattern. Bad credit or no credit does not, by itself, turn someone away if they will work through the items a counselor identifies.

Sources: Purchase product · Mortgage product FAQ · NACA home page, rates dated November 5, 2026 · Qualification workbook 26.6

Rates NACA published, and why they do not all match

On November 5, 2026, NACA’s home page listed a below-market fixed rate of 6.25 percent for 30 years, 5.75 percent for 20 years and 5.875 percent for 15 years. That page did not say which income group those rates were for.

NACA’s purchase-product page, which does not show a date, lists 6.25 percent APR for 30 years and 5.875 percent APR for 15 years for low-to-moderate income people and communities, and 7.25 percent APR for 30 years and 6.875 percent APR for 15 years for higher-income people. It says the APR is subject to change and may not be available at lock-in or commitment.

The same purchase-product page describes the optional buy-down as 1.5 percent of the mortgage amount reducing a 30-year rate by 0.25 percent, and 1 percent of the mortgage amount reducing a 15-year rate by 0.25 percent. Qualification workbook 26.6 describes a different buy-down: 1.5 percent of the loan reduces a 30-year or 20-year rate by 0.25 percent, and a 15-year rate by 0.375 percent. Because those formulas conflict, confirm the current buy-down with NACA before you plan around it.

Sources: naca.com home page · Purchase product · Workbook 26.6

Fit

Who the program can fit, and who it does not

It can fit

Buyers who will live in the home, document income and debts, complete counseling, and accept an affordable payment NACA sets with them. NACA says the mortgage is not limited to first-time buyers. A later purchase is allowed after at least five years, and NACA says a member may purchase through the program twice.

Priority members are described as borrowers whose combined income is at or under the median family income for the metropolitan area where they buy, with a wider choice of locations. Higher-income members are limited to areas NACA treats as priority, generally a census tract at or under that same median, and NACA says those buyers can also receive the lower rate. The exact line at 100 percent of the median is worded differently across NACA’s pages, so ask NACA which status applies to you.

It does not fit

Investors, second homes, and any household that will still own another property at closing. NACA counts a household member as anyone 21 or older who will live in the home. A spouse who will live there and still owns a home makes the household ineligible until that home is sold.

Buyers who will not occupy the home for the life of the NACA mortgage, who will not complete the workshop, counseling, documents and participation pledge, or whose price plus repair escrow would exceed NACA’s acquisition limit or the payment they were qualified for. NACA says you cannot pay the difference yourself to get over the maximum purchase amount.

Sources: General and eligibility · Area eligibility · Real estate FAQ

Income, purchase limits and cash you still need

NACA does not publish one Houston dollar income cutoff on the pages reviewed for this guide. Status depends on combined borrower income compared with the median family income of the metropolitan area where the house is, and then on the census tract. Use NACA’s ZIP code tool for a general estimate, then confirm the address in the FFIEC geocoder before a contract. NACA says the ZIP tool is not specific to one property.

For context only, HUD’s FY 2025 median family income for the Houston-The Woodlands-Sugar Land HUD Metro FMR Area was $101,100. That figure is HUD’s, not NACA’s eligibility line, and a later HUD year may already be in effect. This page did not retrieve a HUD FY 2026 Houston summary.

NACA’s loan-limits page lists a maximum acquisition cost of $766,550 for a one-unit home in most areas and $1,149,825 in high-cost areas, with higher caps for two-, three- and four-unit homes. The price plus any repair escrow cannot exceed the member’s approved maximum mortgage or that cap, and NACA says you cannot get around the cap by bringing cash to reduce the loan. Older FAQ answers on the same site still show lower figures, including a 2023 single-family figure of $548,250 and another answer at $484,350. Use NACA’s county tool for the property. This page does not state whether Harris County or a particular Houston suburb is in the high-cost column, because that row was not in the portion of the tool reviewed here.

No down payment and no closing costs do not mean zero cash. NACA’s mortgage FAQ says members still need minimum required funds: earnest money, which is returned at closing; a home inspection; prepaid property insurance and taxes; and reserves. NACA describes those reserves as one month if payment shock is under $300, two months if it is greater, and four to six months for a multi-family purchase. The typical amount depends on the area, the budget and the property.

Sources: Area eligibility · HUD FY 2025 Houston median · Loan limits · Mortgage FAQ, funds still required · 2023 limit still on the eligibility FAQ · Older limit still on the real estate FAQ
Fees, the lien, and membership

NACA’s eligibility FAQ says the homebuyer workshop and basic counseling are free. Membership is required for the NACA mortgage, additional counseling and other services. That FAQ says the current annual membership fee is $36 per household, prorated at $3 a month, for as long as the member is in the purchase program and has a loan through NACA. The same site’s overview FAQ also contains a sentence that says the fee is $25. Confirm the amount NACA will charge you before you pay. A counselor will not work a file if the current year’s dues are unpaid.

NACA also says there is a nominal fee for credit-report pulls, refunded at closing by the lender. The dollar amount of that fee was not stated on the FAQ reviewed here.

NACA says it records a $25,000 soft-second lien so the member lives in the home for as long as they have the NACA mortgage, and so any payment assistance can be repaid if required. NACA says it can subordinate that lien in some cases, at its discretion. Members do not pay PMI. A former $50 monthly fee does not apply to new NACA mortgages. NACA says it can still apply to certain loans that closed with Bank of America before January 1, 2014, or with CitiMortgage before March 1, 2012.

Sources: Fees, lien and PMI · Overview FAQ, $36 dues and the older $25 sentence

Occupancy and participation

At closing, the house must be the member’s only home. After closing, it must stay the primary residence the member occupies for as long as the NACA mortgage is in place. Selling, refinancing, or buying another property later is allowed only if that occupancy rule is still met. Paying off or refinancing away from the NACA mortgage ends the occupancy requirement.

Membership includes a participation pledge. NACA’s eligibility FAQ requires five actions or activities a year, at least one before NACA qualification and one before closing, in support of NACA’s economic-justice mission. The qualification workbook says the same five voluntary activities a year, with at least one before qualification, continuing for as long as you have a mortgage through NACA. NACA says members participate in whatever way they feel comfortable. Examples it gives include an advocacy campaign, volunteering at an event, helping bring others into the program, and helping others register to vote through NACA. If you are legally eligible to vote, NACA says you must be a registered voter before housing counseling.

Sources: Eligibility FAQ · Purchase product, occupancy · Overview, participation and voter registration · Qualification workbook 24.1, participation pledge

Process

Steps NACA publishes, and a realistic timeline

  1. 01

    Homebuyer workshop

    The first step is NACA’s free homebuyer workshop, about four hours, in person or self-paced online. NACA says each office holds at least two a month, mostly on Saturdays, and that a seat should be available within six weeks. Its counseling department describes the regional workshop as every other Saturday from 9 a.m. to 1 p.m. local time. You do not need financial documents at the workshop. Bring something to take notes. After you finish, NACA says your ID arrives within three business days. The current list is on NACA’s workshop sign-up page. You can attend in a state where you do not live. NACA encourages a workshop in the area where you plan to buy.

  2. 02

    Member portal and intake

    You set up the member portal, which requires a cellphone for two-factor authentication, sign NACA’s agreement, enter your information and upload documents. NACA’s purchase page says that after the portal sections are done, including the membership fee and the credit report, you can schedule intake. Intake is about two hours, at an office or by video. Both people sign the agreement and show a photo ID if a joint credit report will be pulled.

  3. 03

    Counseling and an action plan

    The counselor reviews the budget and documents with you and sets a payment you can afford. NACA says members should expect a follow-up within about 30 days, which can be by video. Complete the action items, including at least one participation activity before qualification. NACA’s business hours are Monday through Friday, 8:30 a.m. to 6 p.m., with limited Saturday counseling.

  4. 04

    NACA qualification

    NACA Qualified means NACA has pre-approved you for its mortgage and you may start the housing search. NACA says many members who stay active are qualified in about three months, and that prepared members can be faster. It says the process should not take more than six months unless there are circumstances such as a foreclosure, bankruptcy or charge-off within the last two years, or liens that have to be paid. Qualification is not a closed loan. NACA’s counseling department says the file is then packaged and submitted to a participating lender, and lender conditions still have to be cleared.

  5. 05

    Property workshop, then the purchase workshop

    NACA’s purchase page says you attend a Property Workshop webinar before qualification, described there as Tuesdays at 6 p.m. Eastern. After you are qualified, a Purchase Workshop is required, described as Thursdays from 6 to 7:30 p.m. at a NACA office or online, covering the search, contracts and the mortgage file.

  6. 06

    Search, contract and closing

    The time to find a house is separate from qualification and depends on the search. NACA recommends against signing a purchase contract before you are qualified, because there may not be time to finish and the house may not fit the payment. NACA says you also need one participation activity before closing.

Plan on months, not a weekend. Use three months as NACA’s figure for many active members, and six months as the outside of what NACA says to expect, unless a recent foreclosure, bankruptcy, charge-off or lien applies. House hunting starts after that. Nothing here is a promised closing date.

Sources: Purchase steps · Qualification FAQ · Counseling department

Credit readiness

Counseling from NACA, not credit repair

NACA’s counselors provide free housing counseling and help with credit readiness. NACA says that work includes budgeting, document preparation and financial management, and that a counselor helps identify which items need to be resolved before a member is mortgage-ready. NACA says it evaluates payment history and does not consider a credit score. No one is turned away for bad credit or no credit if they will work on the roadblocks the counselor identifies. That help is housing counseling through NACA. It is separate from a paid credit-repair company. Nothing on this page promises a credit score, a deleted account, or an approval.

The Consumer Financial Protection Bureau describes credit-repair companies as businesses that charge fees and often promise to raise scores or remove negative items, including items you can dispute yourself for free. A HUD-approved housing counselor, which is how NACA describes its counselors, helps you look at income, credit and whether buying now makes sense. Our separate credit help page explains report errors and how to avoid credit-repair schemes. That page is not NACA, and it is not a credit-repair service.

Sources: NACA counseling department · Workbook 24.1, credit and counseling · Purchase product, credit history · CFPB, credit repair compared with counseling · CFPB, HUD-approved housing counselors

What to gather before intake

NACA says you do not bring documents to the workshop. These are the documents its qualification FAQ lists for qualification and for the intake session. Gathering them early is preparation. It does not qualify you.

A readiness list that is not a NACA approval

Document list: NACA qualification FAQ. Rent payment and the six-month expectation: same FAQ. Minimum funds: mortgage product FAQ.

Houston

NACA’s Houston office, and where Michael works

NACA’s offices page lists a Houston office at 14425 Torrey Chase Blvd, Suite 200, Houston, TX 77014, phone 713-706-3400. The same page lists Dallas and San Antonio offices and prints Texas mortgage broker license number 378153 with the Texas listings. NACA also offers remote video counseling through its counseling center for members who are not near an office or who prefer it. Member services: 425-602-6222.

An office in Houston does not mean every Kingwood, Humble, Atascocita or Lake Houston address is eligible. Priority and non-priority rules depend on income and the census tract of the house. Confirm the address with NACA before you write an offer.

Michael’s brokerage office is Keller Williams Realty Northeast, 20665 W. Lake Houston Pkwy, Humble, TX 77346. That is not a NACA office.

Source: NACA offices · Remote counseling

How Michael helps

House search and timing, while NACA handles qualification

Michael O’Neal works with buyers using the NACA program. He can help you look at homes in Kingwood, Lake Houston, Humble, Atascocita and the rest of Houston, and he can help you time a search so you are not under contract before NACA qualification if that is still your situation. He can also help you keep a list of what your NACA counselor asked you to do. He does not replace the counselor, pull your credit, or decide whether NACA will qualify you.

NACA tells outside agents who want to refer a buyer to register in its Real Estate Agent Portal and to upload a buyer representation agreement. NACA says it does not charge the agent a fee and does not reduce the commission. It also says it will not accept an agreement that charges the member broker fees, transaction fees, retainer fees, nonprofit process fees, or commission above what the seller is paying. Portal registration is an account NACA describes for outside agents. It is not a certification, a partnership, or an endorsement. This page does not describe Michael as a NACA in-house agent.

If you want a conventional, FHA, VA or other loan instead of NACA, that is a different conversation. Home Front Mortgage is an affiliated business. You do not have to use Home Front to work with Michael, and this page does not say Home Front originates NACA loans. See the Home Front page and the affiliated business disclosure.

Neighborhood reading while you wait on counseling: Kingwood, Lake Houston, Humble, Atascocita, the first-time buyer guide, and buying with Michael. Search current listings on the home search.

Questions

Common questions

Consultation

Tell Michael you want to talk about NACA

This is a request for a conversation about homes and timing. It is not an application to NACA, and your answers do not qualify you for anything. Do not include a Social Security number, a credit report, pay stubs, bank statements, account numbers or other financial documents.

Request a consultation

Checked November 6, 2026, against NACA’s public pages linked above, plus HUD’s FY 2025 Houston median family income and CFPB explanations of housing counseling and credit-repair companies. Where NACA’s own pages disagree, this page says so instead of picking a number. The Michael O’Neal Group, Keller Williams Realty Northeast, 20665 W. Lake Houston Pkwy, Humble, TX 77346. Equal Housing Opportunity. NACA determines eligibility.

The Michael O’Neal Group is an independent real estate brokerage team affiliated with Keller Williams Realty Northeast. This website is an independent educational resource and is not operated, sponsored, or endorsed by NACA. NACA determines program eligibility and mortgage qualification. Mortgage terms and program requirements are subject to change. The Michael O’Neal Group, Keller Williams Realty Northeast, 20665 W. Lake Houston Pkwy, Humble, TX 77346. Equal Housing Opportunity.

The O’Neal Insider · Free weekly

Get the Houston Neighborhood Insider.

Local events, neighborhood updates, and real estate insights for the areas you care about. Read the latest edition.

Which areas and topics? Pick any.Areas
Also want text alerts? (optional)